

Award-Winning Company in Insurance
Intro Section
Protection Beyond Individual Homes
A homeowners association is responsible for more than just buildings — it helps manage shared spaces, community safety, maintenance responsibilities, and the overall resident experience. HOA insurance helps provide financial protection for the common property and operations that keep your community running smoothly.
From unexpected property damage to liability concerns and board-related issues, the right coverage helps associations reduce financial stress and stay prepared for the unexpected.
Intro Section
Coverage designed to help protect the shared property, operations, and responsibilities that keep your community running smoothly.
Coverage
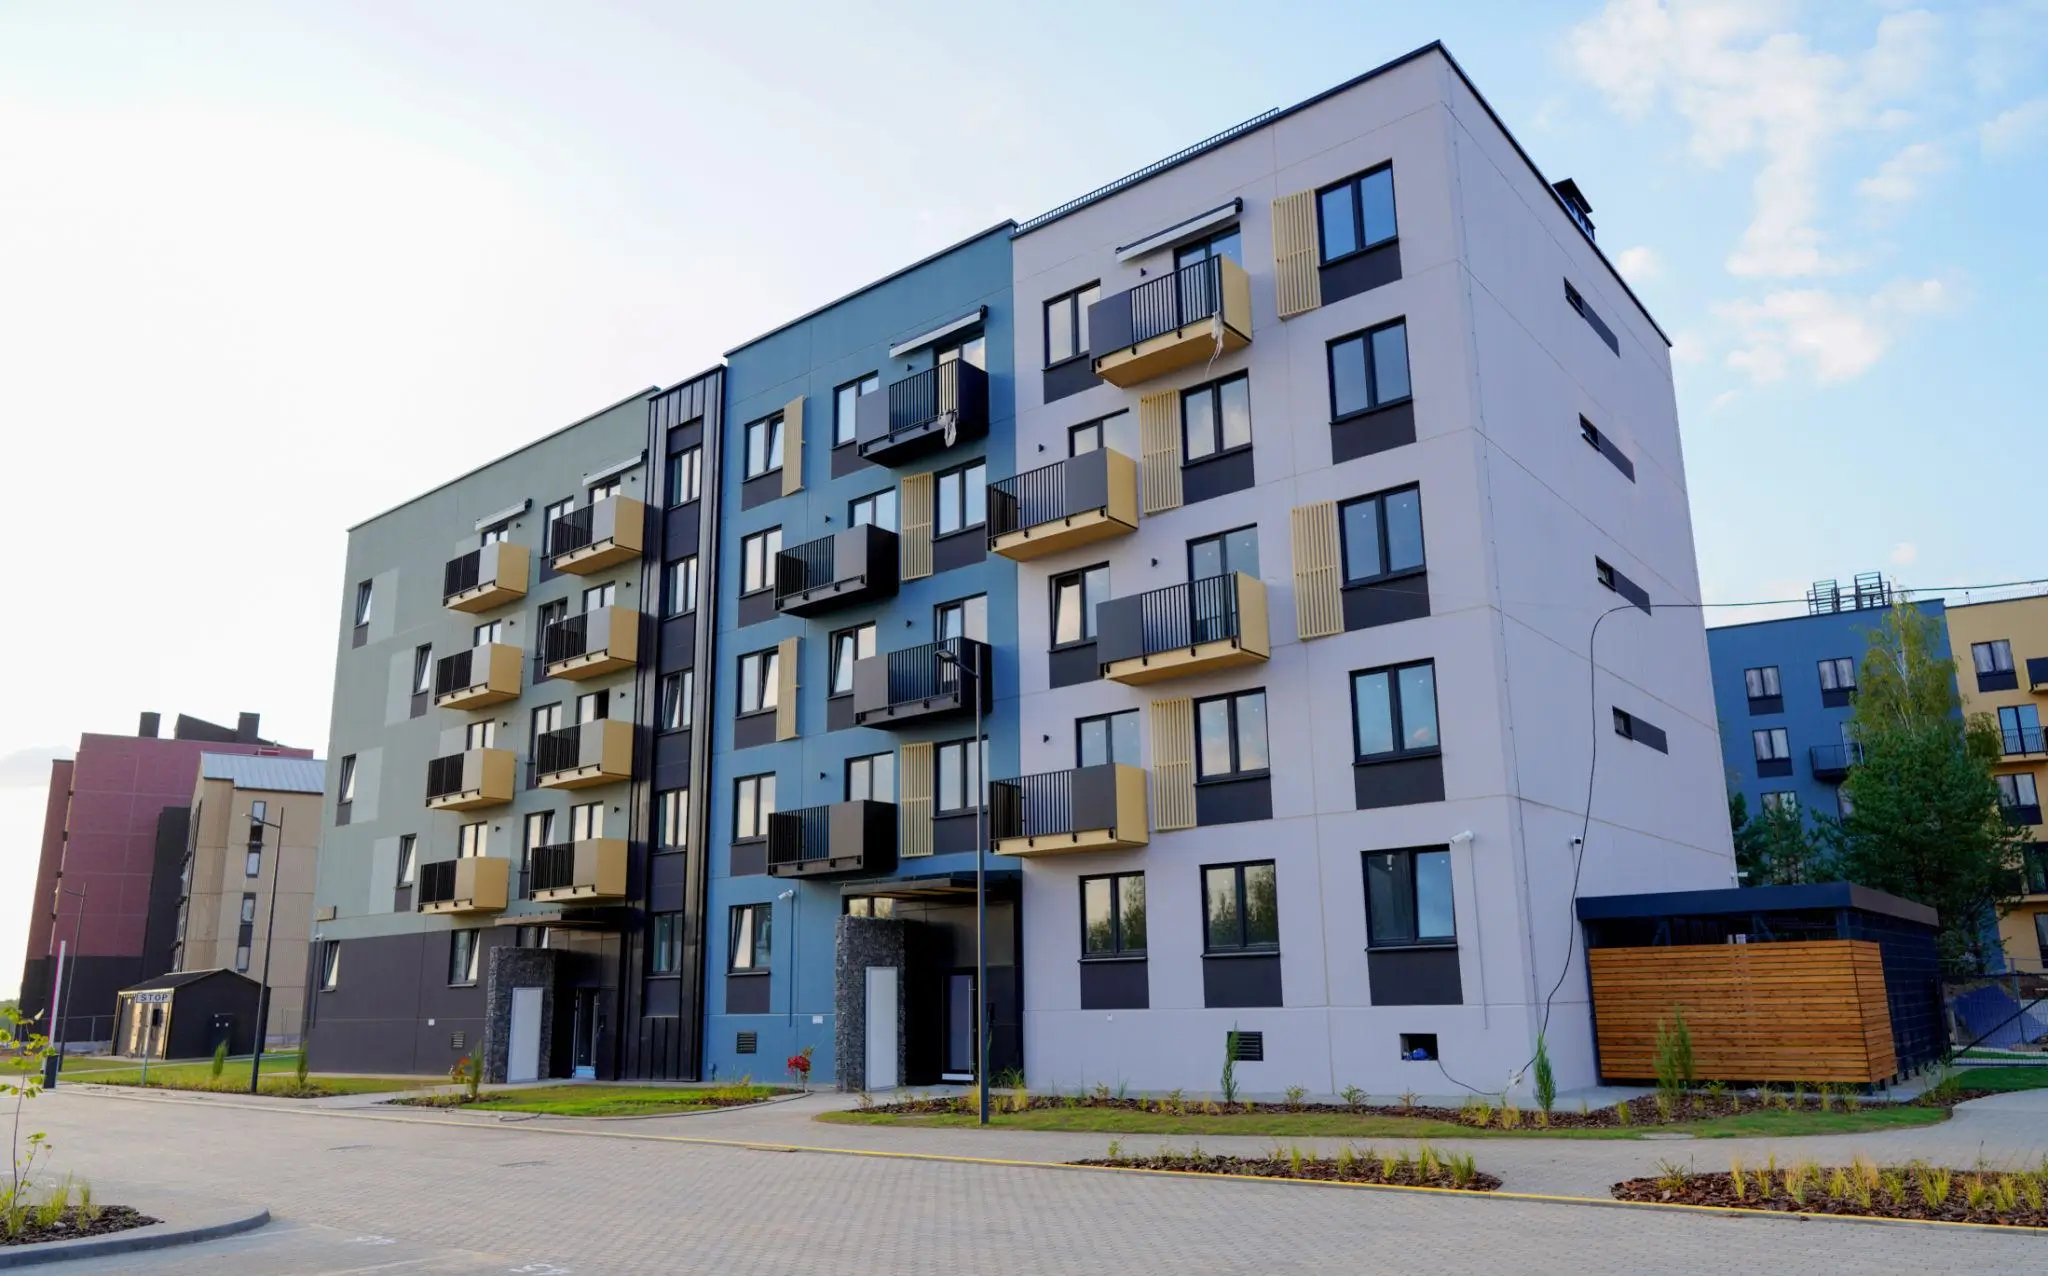
Condominium Associations
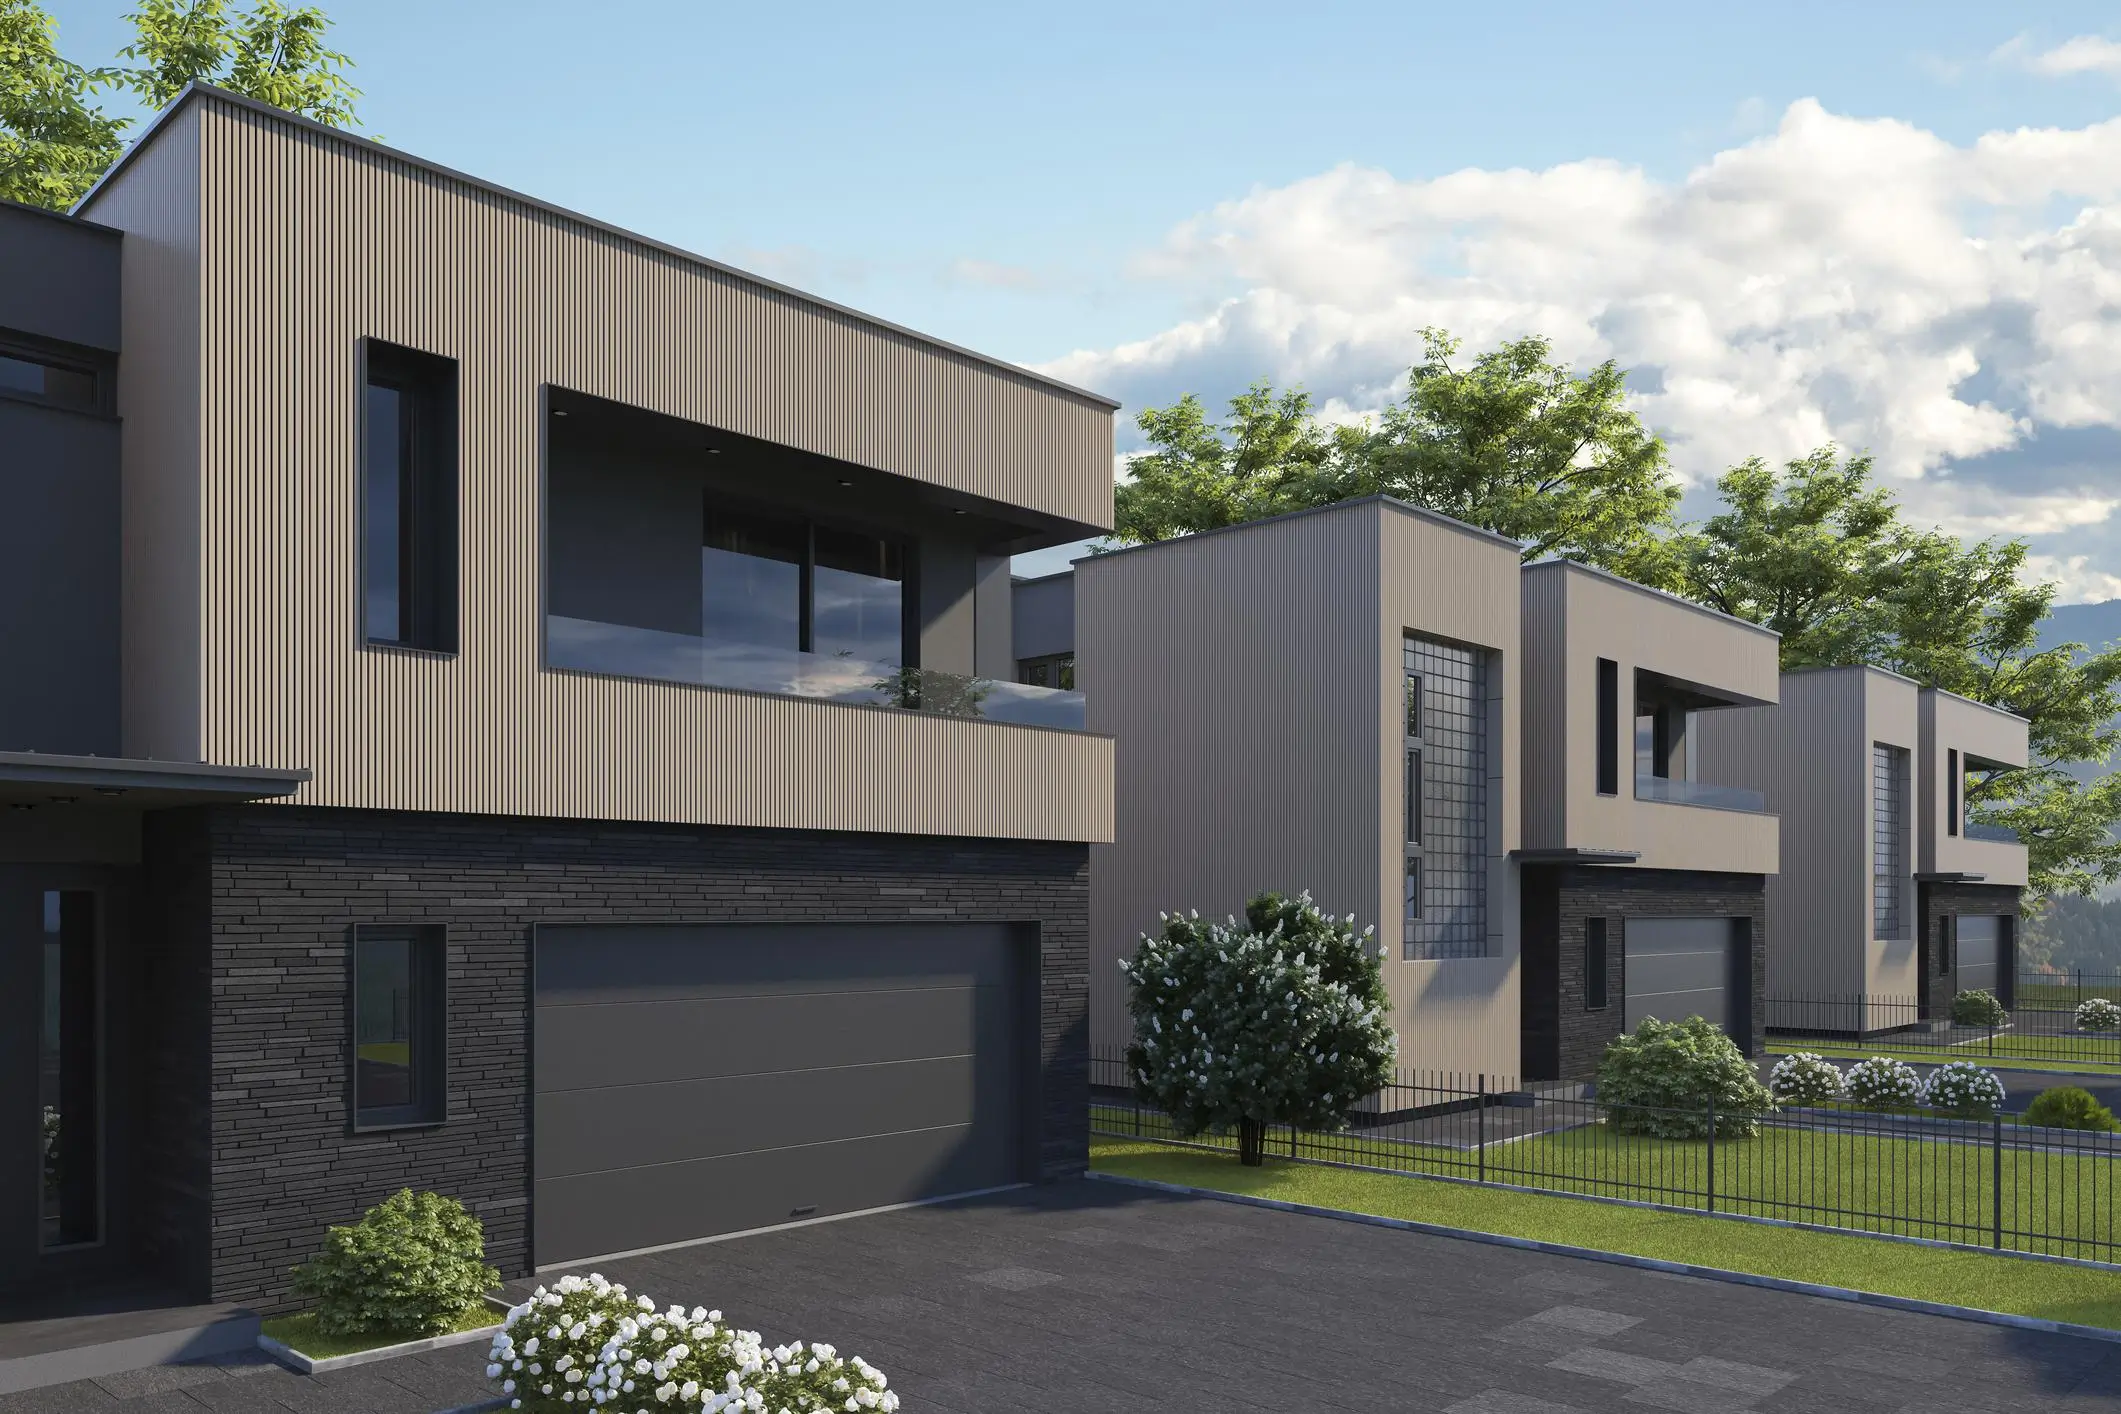
Townhome Communities
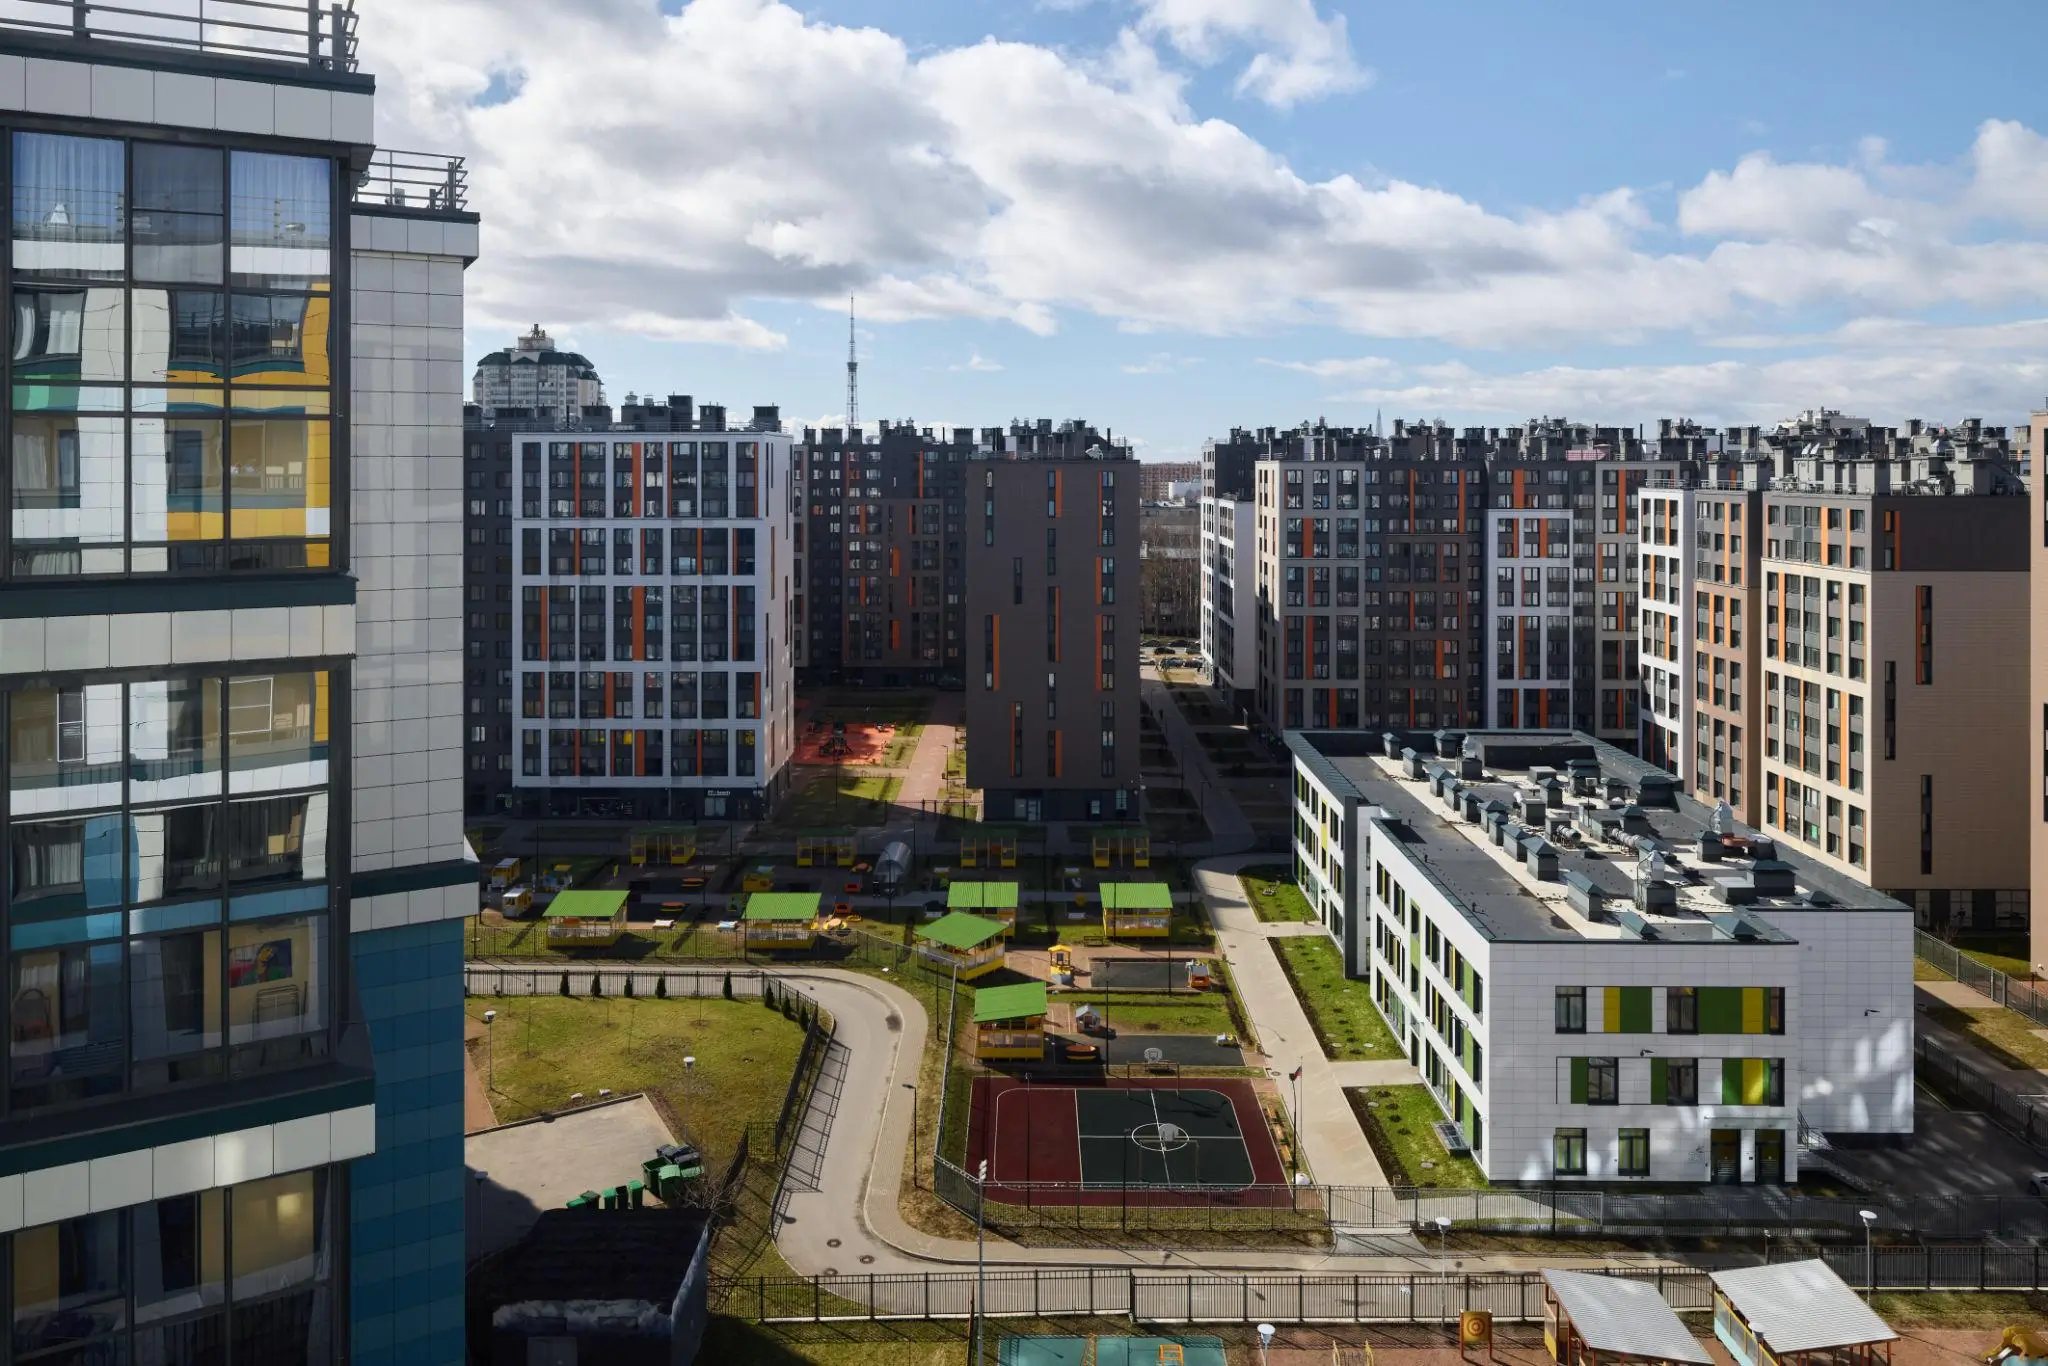
Residential Neighborhood HOAs
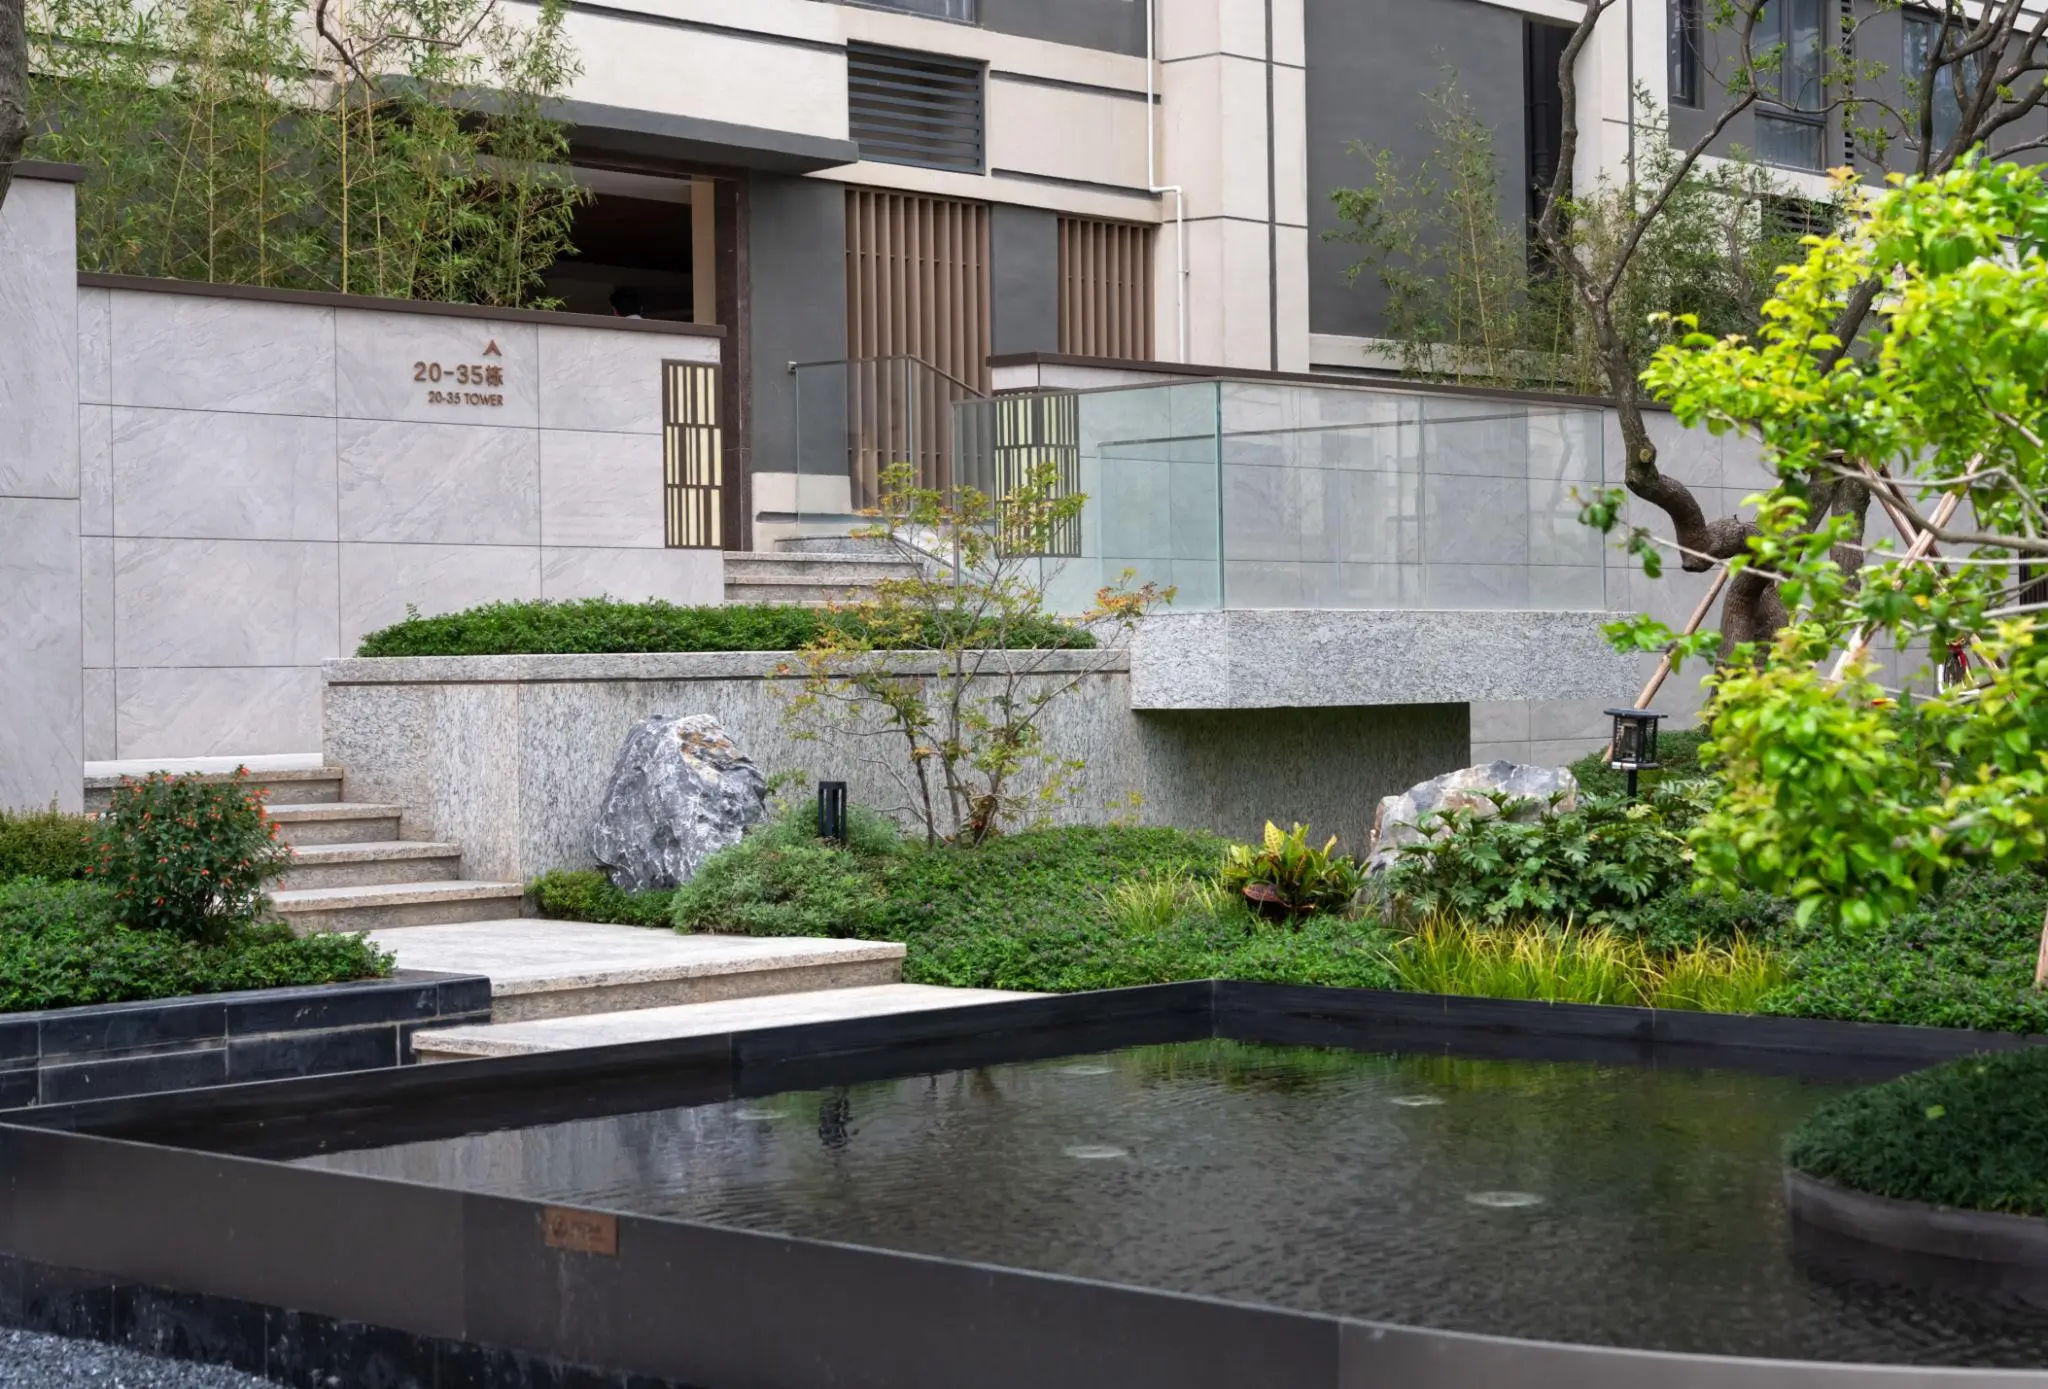
Gated Communities
Planned Residential Developments
Mixed-Use Residential Properties
HOA Insurance Requirements and Regional Risks in Oregon & Washington
regon and Washington associations face risks that don't show up the same way in most national HOA insurance guides:
Oregon HOAs
Washington HOAs
Board Tip
Managing a residential community comes with daily responsibilities and unexpected risks. Property damage, weather incidents, guest injuries, vandalism, or legal disputes can create significant financial challenges for homeowners associations. HOA insurance helps associations protect shared investments, maintain community operations, and support long-term property value stability.
Every association pays a different premium because pricing depends on the size of the community, the age of the buildings, and everything the HOA is responsible for maintaining. A small townhome association with no pool or elevator will typically pay far less than a gated community with a clubhouse, fitness center, and shared parking structure.
Here's what most commonly moves the number up or down for HOA insurance coverage in Oregon and Washington:
Number of units and total square footage of common areas
Age and condition of shared roofs, siding, and mechanical systems
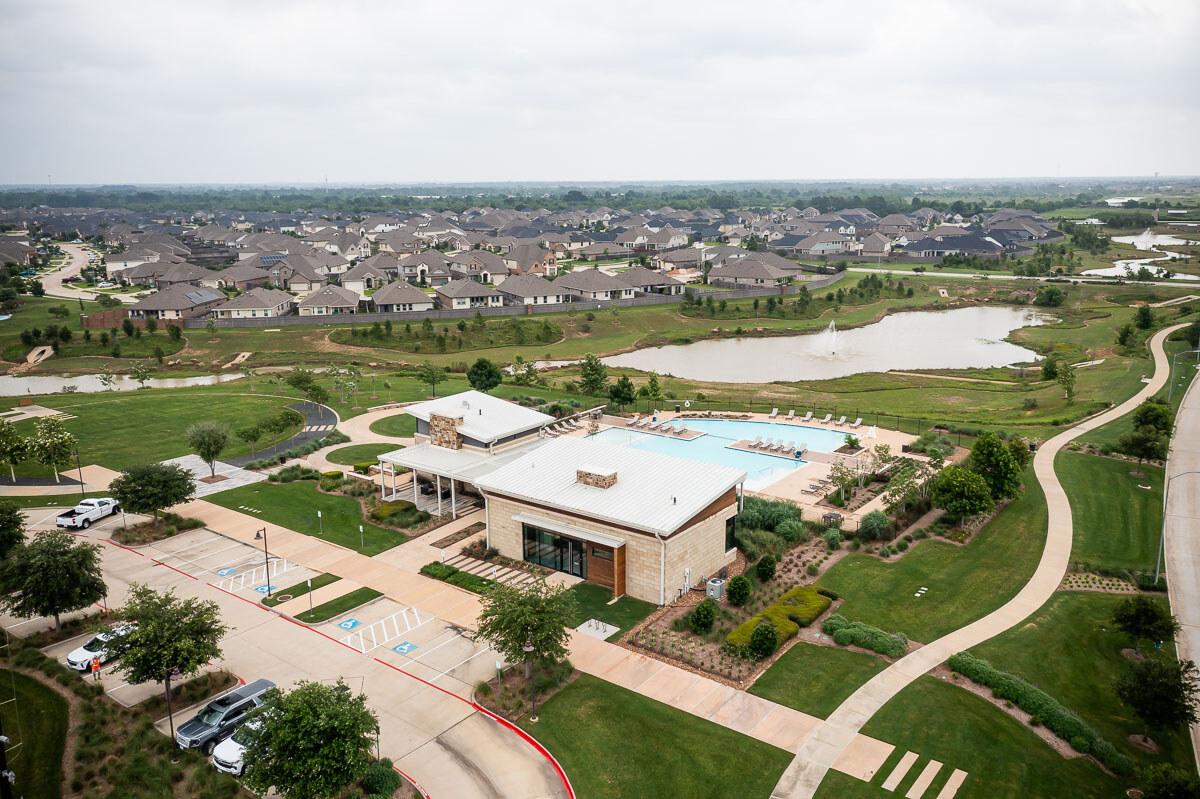
Amenities like pools, elevators, gates, and fitness centers
Claims history for the association over the past five years
Master policy type (bare walls, single entity, or all-in — more on this below)
Regional risk exposure, including wildfire zones in Oregon and windstorm/earthquake risk across Washington
Rather than guessing a number from a generic online calculator, the fastest way to get an accurate figure is to request an HOA insurance quote directly, since a licensed agent can weigh your community's actual risk profile instead of a national average.

If your community is a condo or townhome association, this is exactly why residents are usually required to carry an HO-6 policy alongside the association's coverage — and it's worth reviewing us homeowners insurance page to see how that individual layer fits with your HOA's homeowners' association insurance coverage. Boards that clearly communicate this split to residents see far fewer disputed claims after a storm or water loss.
Bylaws and state condo law often dictate which type an association is required to carry, so this isn't purely a cost decision — it's also a governance one. If your board isn't sure which structure your current policy follows, that's worth clarifying before your next renewal, since it directly affects the commercial property coverage association needs to carry its buildings and shared structures.
Intro
Coverage That Fits Your Community
How It Works
Simple Process. Reliable Protection.
Getting an accurate Hoa insurance quote goes faster when your board has a few things ready ahead of time. Before you call or submit a request, gather:
Current declarations page from your existing master policy, if you have one
Total number of units and square footage of all buildings and common areas
List of amenities — pools, gates, elevators, fitness centers, clubhouses
Recent claims history for the association, typically the last five years
Reserve study or recent appraisal, if available, to help confirm rebuild costs
Board meeting minutes or bylaws noting your required master policy type
Having this ready doesn't just speed up the process — it usually results in a more accurate Hoa insurance quote the first time, instead of a revised number after underwriting asks follow-up questions. When you're ready, our team can walk through all of it on a call — book an appointment or request pricing directly through the quote page.