Hero Bg Image

General Liability Insurance in Oregon & Washington 

Protect your business from everyday liability risks with flexible coverage solutions designed for contractors, small businesses, storefronts, and service professionals across Oregon and Washington.

Hero Bg Image

General Liability Insurance in Oregon & Washington 

Protect your business from everyday liability risks with flexible coverage solutions designed for contractors, small businesses, storefronts, and service professionals across Oregon and Washington.

Hero Bg Image

General Liability Insurance in Oregon & Washington 

Protect your business from everyday liability risks with flexible coverage solutions designed for contractors, small businesses, storefronts, and service professionals across Oregon and Washington.

Hero Bg Image

General Liability Insurance in Oregon & Washington 

Protect your business from everyday liability risks with flexible coverage solutions designed for contractors, small businesses, storefronts, and service professionals across Oregon and Washington.

Protection for Everyday Business Risks

Protection for Everyday Business Risks

Running a business comes with responsibilities and unexpected risks every day. From customer interactions and job site operations to service calls and vendor relationships, even small incidents can sometimes lead to costly liability concerns. General liability insurance helps businesses prepare for covered bodily injury claims, property damage situations, and legal-related expenses that may arise during normal business operations.

Running a business comes with responsibilities and unexpected risks every day. From customer interactions and job site operations to service calls and vendor relationships, even small incidents can sometimes lead to costly liability concerns. General liability insurance helps businesses prepare for covered bodily injury claims, property damage situations, and legal-related expenses that may arise during normal business operations.

Running a business comes with responsibilities and unexpected risks every day. From customer interactions and job site operations to service calls and vendor relationships, even small incidents can sometimes lead to costly liability concerns. General liability insurance helps businesses prepare for covered bodily injury claims, property damage situations, and legal-related expenses that may arise during normal business operations.

0

0

Yrs. of experience

0+

0+

Expert members

0+

0+

Satisfied clients
About Image
Staff image

At Best Coverage LTD, we help businesses throughout Oregon and Washington explore personalized general liability insurance solutions tailored to their industry, operations, and business needs.

Why Liability Protection Matters

Unexpected incidents can happen during everyday business operations. A customer slip-and-fall, accidental property damage, or liability-related claim could potentially affect finances, projects, customer trust, and business reputation.

General liability insurance helps businesses stay better prepared for situations that could interrupt operations or create unexpected legal and financial challenges.

Having dependable liability protection in place can help provide greater confidence while focusing on running and growing your business.

Contractor Insurance Requirements in Oregon and Washington, Side by Side

Contractor Insurance Requirements in Oregon and Washington, Side by Side

Both states tie liability insurance to your contractor's license, but they handle it differently. Oregon's Construction Contractors Board (CCB) sets the minimum by license endorsement. Washington's Department of Labor & Industries (L&I) sets one baseline for registration. If your crew works on both sides of the Columbia River, one policy has to satisfy both, and that is where general liability insurance in Oregon and Washington gets confusing. Here is how the two compare.

Both states tie liability insurance to your contractor's license, but they handle it differently. Oregon's Construction Contractors Board (CCB) sets the minimum by license endorsement. Washington's Department of Labor & Industries (L&I) sets one baseline for registration. If your crew works on both sides of the Columbia River, one policy has to satisfy both, and that is where general liability insurance in Oregon and Washington gets confusing. Here is how the two compare.


Oregon (CCB)
Oregon (CCB)
Washington (L&I)
Washington (L&I)

Who sets the rule 

Construction Contractors Board 

Department of Labor & Industries 

Minimum general liability 

Depends on your endorsement. For example, $500,000 per occurrence for a residential general contractor, up to $2,000,000 for a Level 1 commercial general contractor 

$200,000 public liability plus $50,000 property damage, or $250,000 combined single limit 

Proof of coverage 

Your insurer files a certificate with the CCB 

L&I must be listed as the certificate holder 

Also required

Surety bond, plus workers' comp if you have employees 

Surety bond, plus workers' comp through the state system if you have employees 

Treat those numbers on the floor. General contractors, property managers, and commercial clients often ask subcontractors for $1 million per occurrence and $2 million aggregate, and many want to be named as an additional insured. A policy that only meets the state minimum can get you licensed and still cost you the bid. 

Good general liability insurance coverage for contractors is built around the contracts you actually sign, not just the license you hold. Tell us your trade, your CCB endorsement or L&I registration type, and where your jobs are, and we will help you set limits that work in both states. Have employees? Our workers' compensation coverage page explains how that policy sits next to your liability coverage, and our guide on why business insurance matters for growing companies helps when your crew is getting bigger. 

Coverage

Coverage Designed Around Your Operations

Best Coverage LTD helps businesses across Oregon and Washington explore dependable general liability insurance solutions tailored to their operations and future growth.
Reel image

Bodily Injury Protection

Coverage that may help protect businesses if a customer, visitor, or third party experiences a covered injury related to business operations.

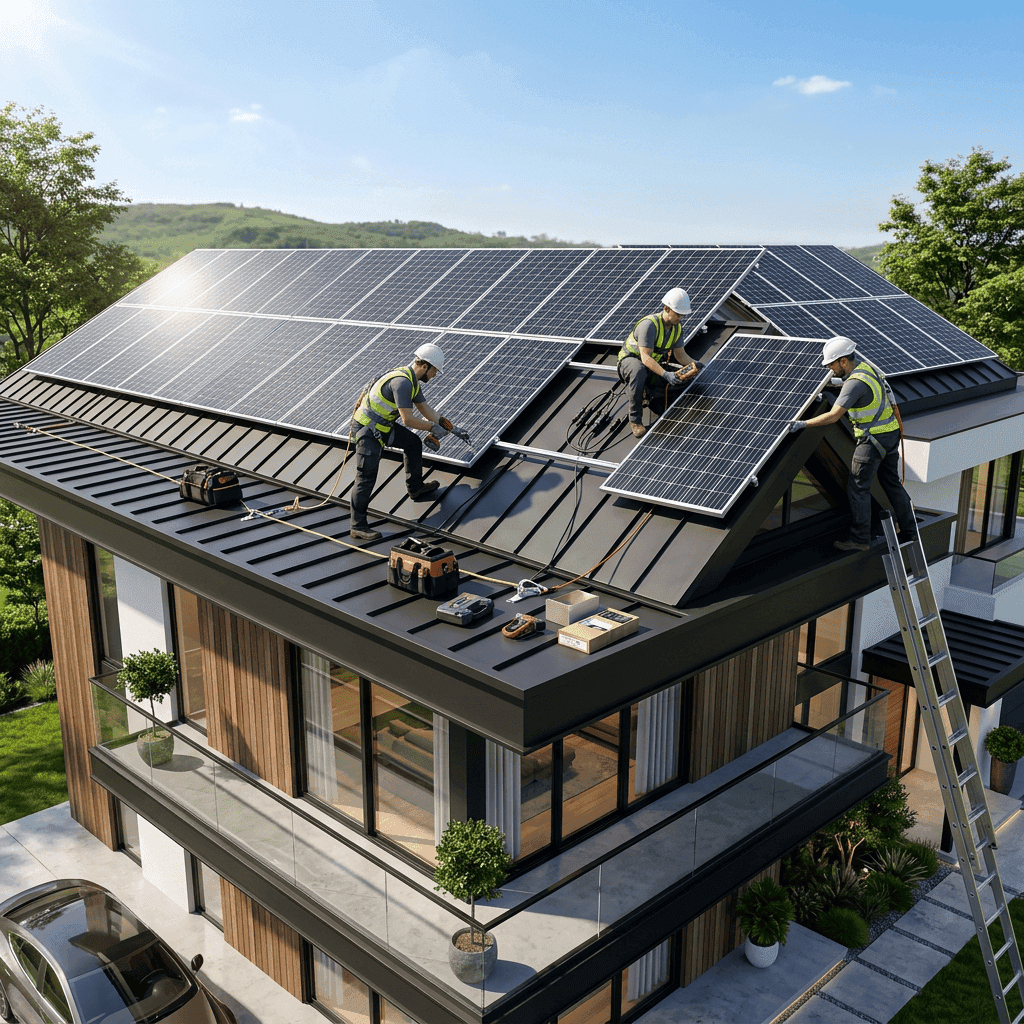
Workers install solar panels on a modern house roof.

Residential Solar Installation

Installing efficient rooftop solar panels to power homes with clean renewable energy solutions daily.

What General Liability Covers, and What It Leaves Out

General liability pays when your business causes harm to someone else. It is not a catch-all, and knowing where it stops saves a lot of frustration at claim time. Business liability insurance in Oregon and Washington typically works like this, though exact terms depend on your policy. 

Usually Covered
  • Bodily injury to a third party, like a customer who trips on your equipment at a job site or in your shop

  • Damage you cause to someone else's property, like a plumber's leak ruining a finished floor

  • Completed operations claims, where work you finished earlier causes damage or injury later

  • Personal and advertising injury, such as a claim over something in your marketing 

  • Legal defense costs for covered claims 

!

Usually Not Covered
  • Injuries to your own employees, which belong under workers' compensation

  • Advice or design mistakes, which belong under professional liability insurance

  • Your own tools, equipment, and building, which belong under commercial property insurance

  • Vehicles used for business, which belong under commercial auto insurance

  • The cost of redoing your own faulty work. The damage it causes may be covered, but the repair of the work itself generally is not 

Coverage

Businesses We Commonly Help Protect

General liability insurance may benefit many different industries and business types that interact with customers, vendors, properties, or the public during daily operations.

Common Businesses Include:
  • Contractors & Construction Companies
  • Delivery & Courier Businesses
  • Electricians & HVAC Companies
  • Landscapers & Outdoor Services
  • Plumbing Businesses
  • Cleaning & Janitorial Services
  • Food & Catering Businesses
  • Service Fleets & Mobile Businesses

Every business operates differently, which is why coverage needs may vary depending on services, operations, and exposure to risk.

Every business operates differently, which is why coverage needs may vary depending on services, operations, and exposure to risk.

Protection That Grows With Your Business

As businesses grow, operational risks and liability exposure may also change over time. Expanding services, hiring employees, taking on larger projects, or opening additional locations can all create new insurance considerations.

Best Coverage LTD helps business owners review flexible general liability insurance solutions designed to evolve alongside their operations while helping provide dependable protection for current and future business needs.
Team members
Team members

General Liability Insurance Coverage for Contractors: Limits, Certificates, and Additional Insureds 

Winning commercial work often comes down to paperwork. Before you start, the general contractor or property owner will ask for a certificate of insurance (COI). This is what they look for, and what to check before you hand it over:

  • Limits. $1 million per occurrence and $2 million general aggregate is a common ask. Larger projects may want more, which is where an umbrella policy can sit on top of your base coverage.

  • Additional insured endorsement. This lets the GC or owner be named on your policy for claims tied to your work. It is added by endorsement, so it does not happen automatically.

  • Primary and non-contributory wording. Some contracts require your policy to respond first. Check the contract language.

  • Waiver of subrogation. Another common contract request. Ask for it before you bid, not after you win.

  • Completed operations. Confirm it is not excluded, especially on remodel and repair work where problems show up after you leave.

  • Named insured. The business name on the COI should match your contract and your license.

A COI is a snapshot, not the policy. It proves coverage exists, but it does not change what the policy actually covers. If a client asks for something your policy does not include, you want to learn that before you sign, which is the case for sorting out general liability insurance in Oregon and Washington early instead of mid-project.

Not sure what happens after you report an incident? Read how business insurance claims work.

What Affects the Cost of Business Liability Insurance

What Affects the Cost of Business Liability Insurance

There is no flat rate. Premiums come down to how likely a claim is and how expensive it could get. Business liability insurance in Oregon and Washington is priced mainly on these factors: 

There is no flat rate. Premiums come down to how likely a claim is and how expensive it could get. Business liability insurance in Oregon and Washington is priced mainly on these factors: 

Factor
Factor
Why it matters
Why it matters
What you can do
What you can do

Trade and class of work

Roofing and work at height rate higher than painting or cleaning 

Describe your work accurately, including what you do not do 

Payroll or revenue

Contractor policies are often rated on payroll or sales, and the final premium may be audited 

Give realistic numbers so an audit does not surprise you 

Subcontractors 

Uninsured subs can add cost at audit

Collect a COI from every sub, every year

Claims history and safety habits 

Fewer and smaller claims help at renewal 

Keep written safety procedures, signed contracts, and job photos 

Limits and deductible 

Higher limits cost more; a higher deductible can lower the premium

Match limits to your contracts, not to a guess 

If you also need property coverage, a business owner's policy (BOP) can combine general liability and property in one package, often for less than buying them separately. Eligibility depends on your trade and size, and some contractors will not qualify, so ask early. 

The most useful thing you can bring to a quote is your real contract requirements. General liability insurance coverage for contractors is cheapest when it is sized correctly the first time, with no surprise endorsements added mid-job. Ready to see numbers? Request a quote. 
Most Frequently Asked Questions (FAQs)

My Oregon CCB license is active. Does that cover me for jobs in Washington?

No. Oregon's license does not authorize work in Washington. Washington contractors register with L&I, which requires its own bond and proof of liability insurance, with L&I listed as certificate holder. Many policies can be written to cover operations in both states, so ask your agent to confirm that your general liability insurance in Oregon and Washington is set up for the jobs you take.

Is the state minimum enough for a commercial job?
If I stop taking new jobs, should I keep my policy?
If my subcontractor has their own insurance, do I still need mine?
How quickly can I add a client as an additional insured?
I do work for HOAs and property managers. What will they ask for?
I own a rental property and also run my own company. Can one policy cover both?
I run a cleaning company, not a contracting company. What should I check on my policy?
Best Coverage LTD logo

Let's protect your future together

Best Coverage LTD logo

Let's protect your future together

Best Coverage LTD logo

Let's protect your future together

Best Coverage LTD logo

Let's protect your future together

Best Coverage LTD logo

Let's protect your future together