
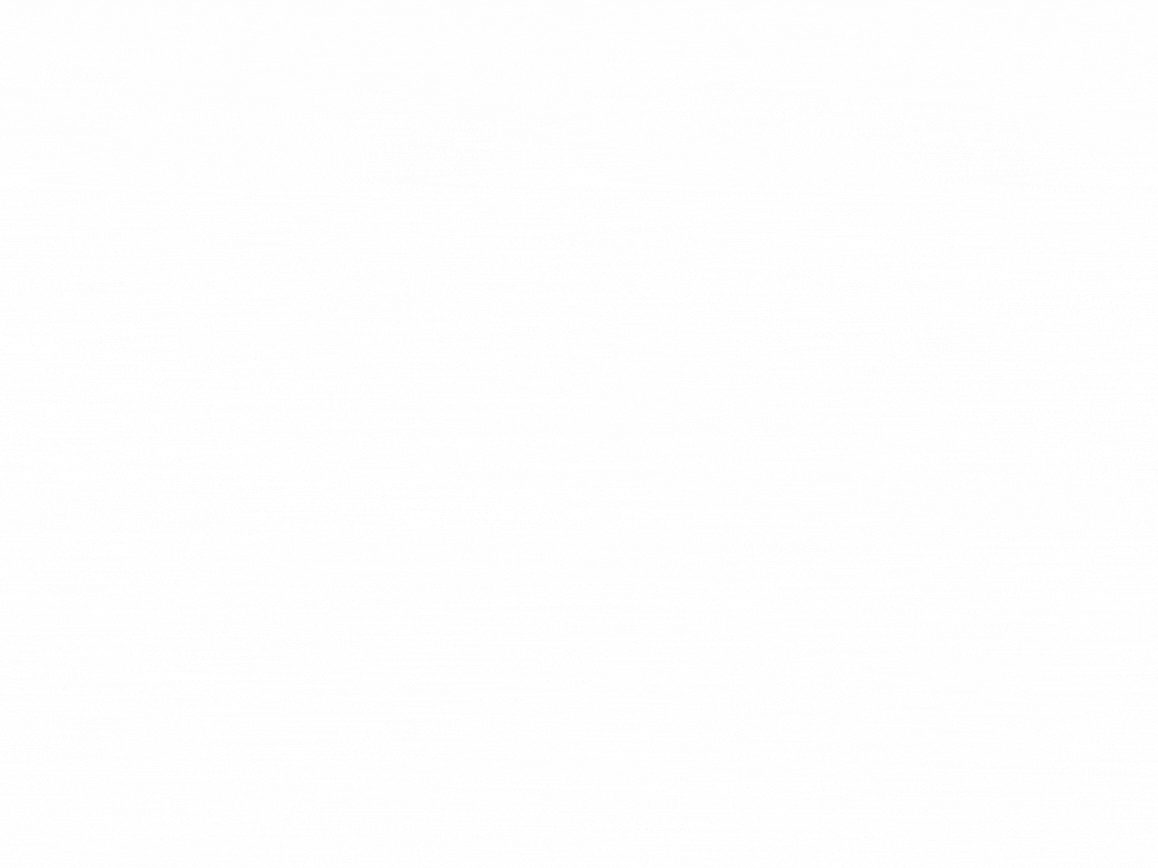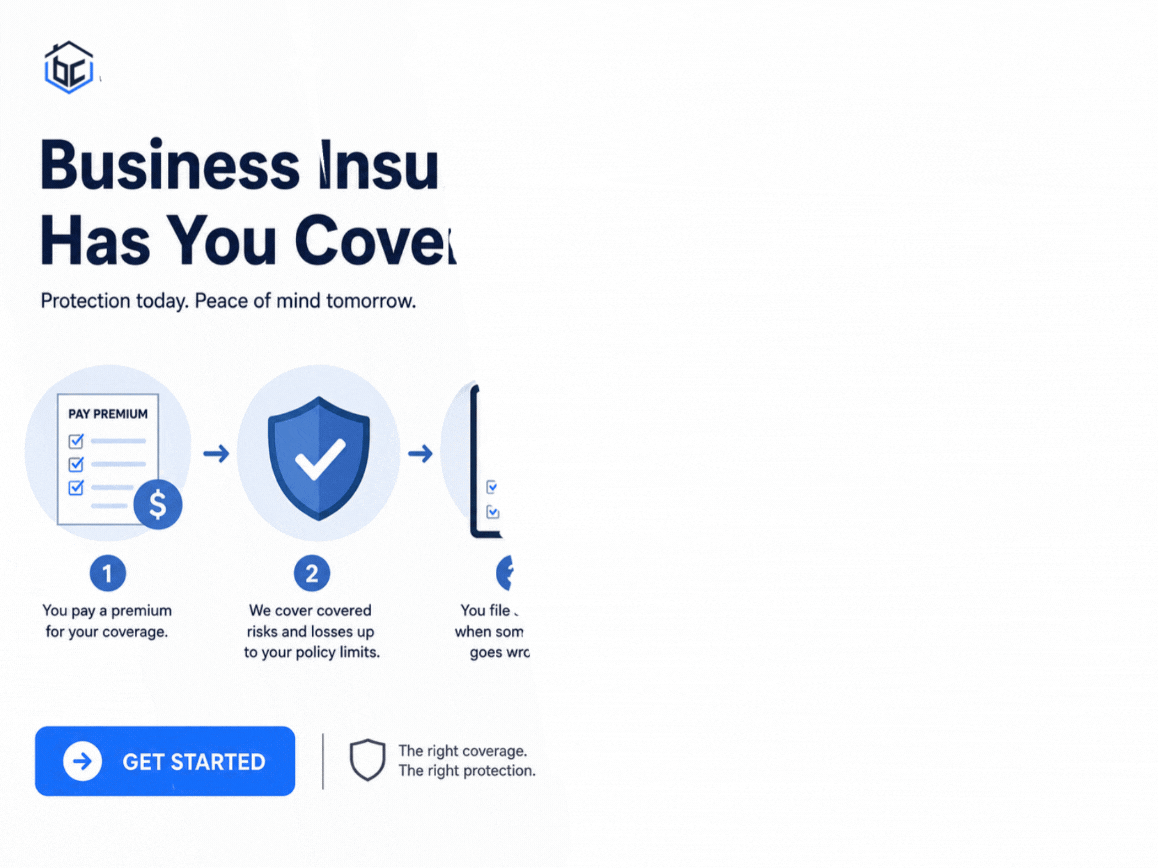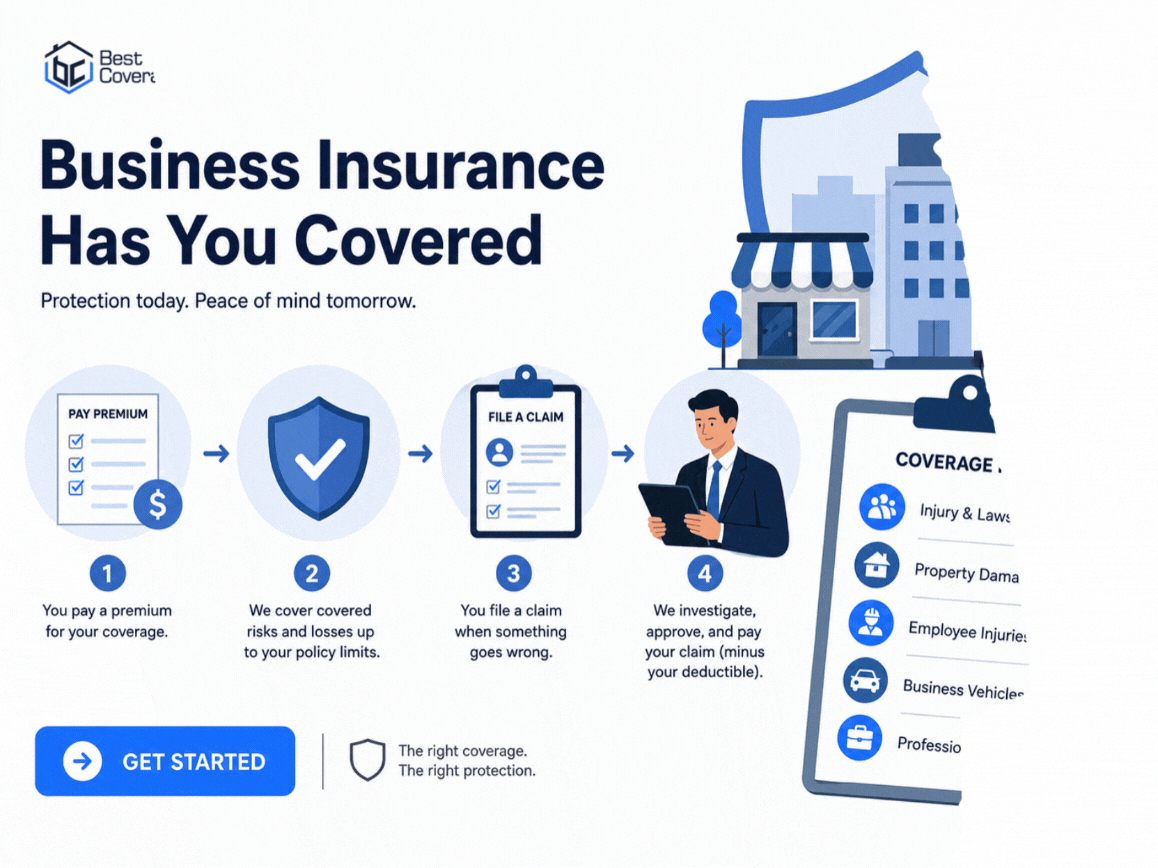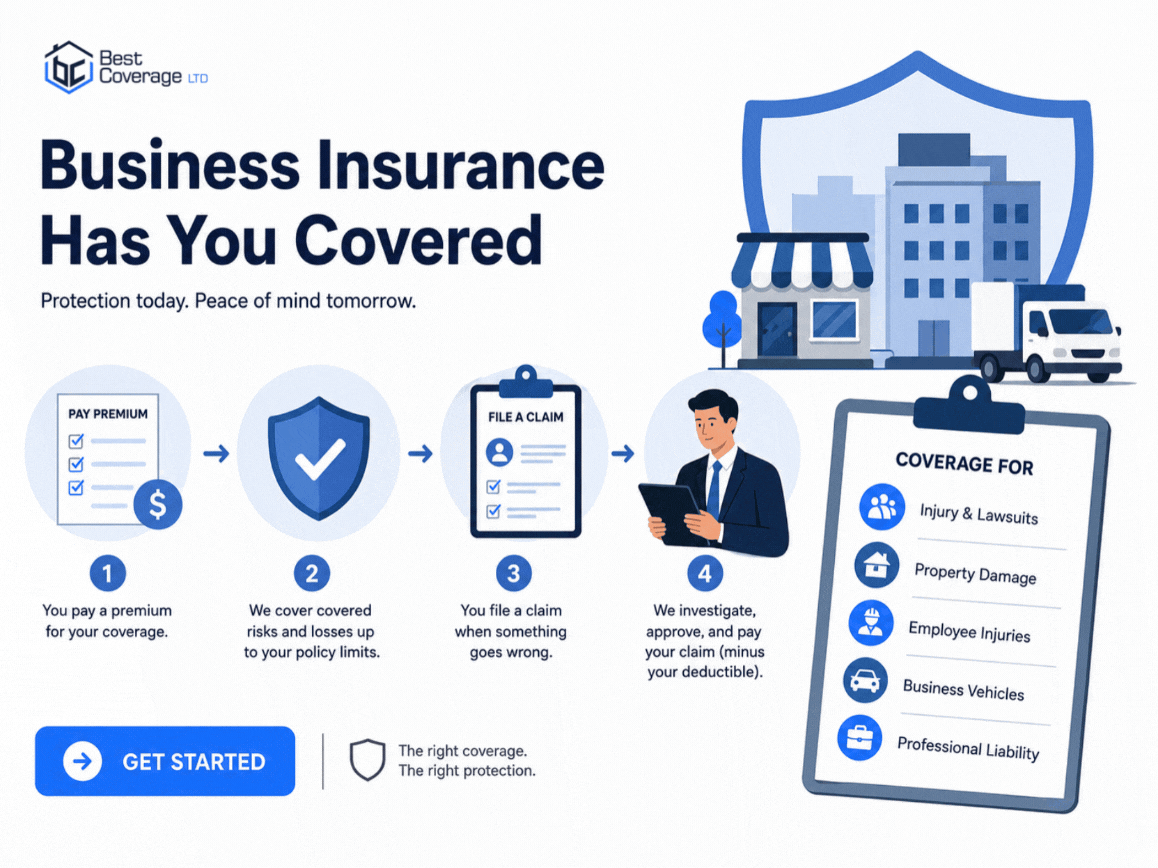
Quick Answer: Business insurance works by pooling risk: you pay a premium, and in exchange your insurer agrees to cover specific losses — lawsuits, property damage, injuries, and more — up to your policy limits. When something goes wrong, you file a claim, an adjuster investigates, and the insurer pays based on your coverage and deductible. Most small businesses combine several policies, often starting with a Business Owner's Policy, to cover the risks that matter most.
What Business Insurance Actually Covers
Here's the thing most people miss about business insurance isn't one policy; it's a stack of them; each built for a different kind of loss. A restaurant owner worries about a customer slipping on a wet floor. A contractor worries about a truck getting totaled on the way to a job site. A consultant worries about a client claiming bad advice to cost them money. Each of these risks' lives under a different type of coverage and understanding which one applies to your situation is the real starting point. If you're not sure where to begin, our general liability insurance page breaks down the coverage most businesses need first.
The Core Policies Every Owner Should Know
General liability insurance is a type of coverage that protects against third-party injury and property damage claims — it's usually the foundation. A Business Owner's Policy bundles general liability with commercial property coverage into one package, which is why it's often the most cost-effective option for small businesses. If you have employees, workers' compensation coverage is typically required by state law and pays medical costs and lost wages after a workplace injury. And if your business relies on vehicles, commercial auto insurance covers accidents involving company-owned or leased vehicles, which is separate from your personal auto policy. Service-based businesses — accountants, consultants, designers — usually need professional liability insurance on top of general liability, since it covers claims of negligence or errors in the advice or service you provided.
How Premiums and Underwriting Actually Work
This is where it gets interesting. Before you ever pay a premium, an underwriter evaluates your business: industry, revenue, claims history, location, and risk exposure all factor into the price. A roofing company will pay more for general liability than a bookkeeping firm, simply because the odds of a costly claim are higher. In most cases, insurers use industry classification codes to standardize this pricing, which is why two businesses in different fields can pay very different premiums for what looks like similar coverage. Your deductible — the amount you pay out of pocket before coverage kicks in — also shapes your premium; a higher deductible usually means a lower monthly cost. If your risk profile is complex, it's worth a real conversation rather than guessing, and our commercial property insurance team can walk through how underwriting affects your specific quote.
How Business Insurance Claims Actually Work
So how do business insurance claims work once something actually happens? First, you report the incident to your insurer, ideally within 24 to 48 hours — delays can complicate the process. The insurer assigns a claims adjuster, whose job is to investigate the loss, review your policy terms, and determine what's covered. For a property claim, that might mean an on-site inspection; for a liability claim, it usually means gathering incident reports, witness statements, and any relevant documentation. The adjuster then calculates the payout based on your coverage limits and subtracts your deductible. According to the Insurance Information Institute, claims involving third-party injuries or lawsuits tend to take longer to resolve than straightforward property damage claims, since legal review adds time. Underwriting and claims are two sides of the same coin: underwriting decides what you're covered for, and claims decide how that coverage gets applied when a loss occurs.
Where Businesses Get This Wrong
Here's an honest take: most businesses are either underinsured or carrying overlapping coverage they don't need, and both mistakes cost money in different ways. A general liability policy alone won't help if an employee is injured on the job — that requires workers' compensation, which the National Association of Insurance Commissioners notes are mandated in nearly every state for businesses with employees. On the other end, businesses that already carry high liability limits sometimes still lack an umbrella policy, which extends coverage beyond your primary policy limits when a major claim exceeds them. If your existing limits feel thin against your actual risk, our umbrella insurance coverage is designed exactly for that gap.
Getting the Right Coverage for Your Business
There's no single "correct" business insurance package — a home-based consultant and a five-truck logistics company need entirely different structures, and pretending otherwise is how businesses end up either overpaying or exposed. The right approach starts with an honest look at your specific exposures: employees, vehicles, physical property, client relationships, and industry risk. From there, coverage should be built around what could actually hurt your business financially, not just what's cheapest to bind today. If you'd rather talk it through than guess, our team can help you get a quote built around your actual operations, or you can contact us directly with questions about coverage or an existing claim.
Frequently Asked Questions
Q: What is business insurance?
A: Business insurance is a set of policies that protect a company from financial loss due to lawsuits, property damage, employee injuries, and other covered risks. Coverage is typically customized by industry and business size.
Q: How does business insurance work?
A: You pay a premium in exchange for coverage against specified risks, up to your policy limits. When a covered loss occurs, you file a claim, and the insurer pays out after subtracting your deductible.
Q: What's the difference between general liability and a Business Owner's Policy?
A: General liability covers third-party injury and property damage claims alone, while a Business Owner's Policy bundles general liability with commercial property coverage into a single, typically discounted package.
Q: How do business insurance claims work?
A: You report the loss to your insurer; an adjuster investigates and reviews your policy, and the insurer determines the payout based on your coverage limits and deductible. Simple property claims often resolve faster than liability claims involving third parties.
Q: How long does a business insurance claim take to resolve?
A: Straightforward property claims can be resolved in a few weeks, while liability claims involving injury or legal disputes often take several months due to investigation and negotiation.
Q: Do I need workers' compensation if I only have one employee?
A: In most states, yes — workers' compensation is required once you have even a single employee, regardless of whether they're full-time or part-time.